Friday, March 23, 2012

Confessions of an Active Manager

As I look back to the early years of my career as a financial advisor, I recall being driven by three powerful and distinct motivating forces. The first was was necessity. With a wife and three children completely dependent on my commissions, success was not a dream or a goal, it was a necessity. But it was alright, I was also strongly motivated by youthful idealism. Success would come because I was devoted to doing a great job for my clients.

The third powerful motivator was a competitive nature. In fact all the brokers I knew seemed to posess similar characteristics. Our employers understood our motivations very well and were quite intentional about the kind of people they hired. They were expert at using these motivators to great advantage, both for themselves and for us.

The numbers game of sending out so many mailers, followed by so many telephone calls, followed by so many in-person meetings led to so many new clients. It became monotonous at times, but I remained motivated out of need, idealism, and competition. The last, competition was almost constantly fed, by an uninterrupted stream of sales contests.

There were contests for selling limited partnerships of oil & gas, real estate development and apartments and investment tax credits. There were even low income apartment deals designed specifically to lose money for our wealthy clients’ tax write-offs. The top tax bracket was 70% then. There were mutual fund wholesalers in our offices constantly and each one had an incredible promotional incentive trip to some exotic locale. One had to wonder how the company could afford such extravagance and still make any money for the target of their funds (were we the target or were our clients the target?).

After a brief stint with the partnerships and funds, I gravitated toward individual securities (particularly stocks) and managed money (particularly growth). I moved most of my clients into my firm’s portfolio management platform which worked pretty well for a while, but I quickly found myself apologizing or explaining moves that I would not have made myself. I became convinced I could do a better job for my clients. What’s more there would be no one with which to share the credit or the blame. That thought had a strong appeal to my competitive nature.

Inspired by great managers of the time like Warren Buffett, Peter Lynch, and John Neff, I read extensively and trained myself and then received formal training at my subsequent firm, Wheat First Securities. My foray into full-time discretionary management coincided with the early days of the Information Age. As an early technology adopter of PCs and the requisite software to make my job easier, I was strongly convinced of the powerful wave that was to sweep our economy, well in advance of the average investor, or money manager for that matter. I had an advantage that Peter Lynch called buying what you understand. Peter believed that individual investors had inherent advantages over large institutions because the large firms would not or could not invest in smaller companies because the value of the company was too small to make a meaningful impact on their assets, or because they were not yet on analysts’ and fund buyers’ radar. As an early adopter of technology, it became my investing expertise.

As the Information Age rolled along, I became fascinated with the growing wave of “disruptive destruction” where older technologies were being replaced by new ones. It seemed the cycles of destruction were becoming shorter and shorter at an exponential rate. Even the traditional rules of investing were being thrown out by many experts. The old value metrics seemed ill-suited to meet the light-speed requirements of the new “Information Age.”

As our returns and success compounded during the 90’s, our clients began to adjust their lifestyles in remarkable ways and we could not have been happier for them (or ourselves). Common were phone calls from ecstatic clients thanking us that they could put in a pool, re-decorate the house, buy a sailboat, or a Porsche - for cash!, or take that pan-European trip with the whole extended family. Some even took extended sabbaticals to spend their new-found treasure. Prospective clients were waiting in line to sign with us, enthusiastically recommended by our clients for our money-making abilities.

Our aggressive growth model attracted the most attention. From March 1990 through March 2000 the model generated a compound return of 26% per year for clients. Over those 52 quarters returns were as high as 59% in a quarter! For thirty five quarters or two thirds of the time, clients received positive return reports from us. And more than half of them were above the 30-year averages for stocks at the time which was 12%.

Of course there were some big losers too. The worst quarter saw a decline of 57% and seven quarters saw losses of greater than 10% (40% annualized). It was interesting how huge gains made people more accepting of huge losses, but the real tests would come.

In March of 2000 the Internet Bubble exploded sending stocks tumbling. The NASDAQ, home of most technology stocks at the time fell 50% by the end of 2000. It would fall another 25% for a total of 76% to its bottom reached October of 2002. The S&P fell 43% before it bottomed the same time. Of course, in addition to the Internet crash, there were other ‘disruptions’ such as 911, war with Iraq, accounting scandals and Enron.  
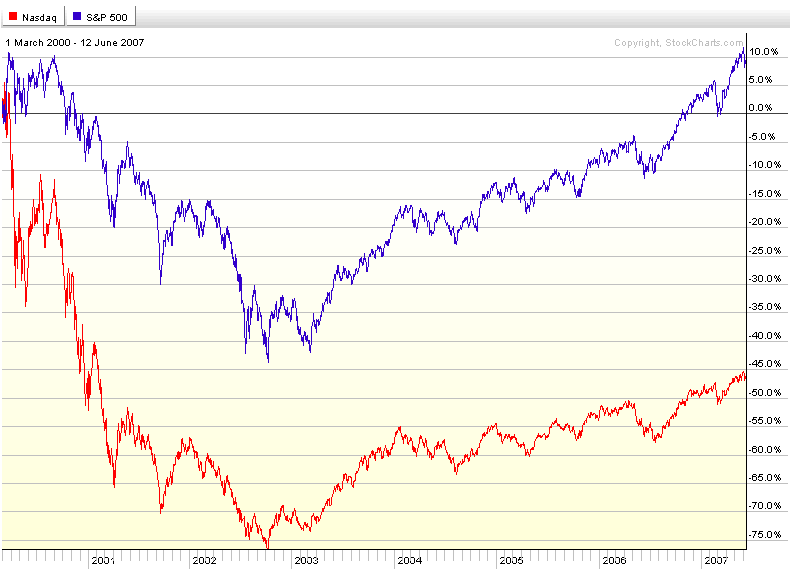


Needless to say, these events coupled with huge mounting losses took their toll on our client base. The new clients, the ones we refer to in the industry as “hot money clients” (those who chase top returns) were the first to leave. Then some of our older clients began to leave convinced we would not recover their losses. While we added significant diversification, moving away from technology, our portfolios continued to decline with the markets. Growth stocks were dead and value stocks were in.

During this time Alan Greenspan, Chairman of the Federal Reserve took interest rates to record lows and began pumping money into the economy to replace the billions that had evaporated in the stock market. The next wave of funds leaving came when low rates began a bull market in real estate – and the next bubble began to inflate. My argument that stocks were cheap and would come back with far better returns than real estate carried little weight.

While my clients had done better than the benchmarks we used to measure their performance and they had more money than they would have had if they invested themselves, they were still leaving, unhappy. Even though I had accomplished my objectives of beating my benchmarks, I had somehow fallen short of meeting the expectations of my clients.

Soon after reaching this stark realization, I had a Damascus road experience. It came through three close friends. The first was a client who left saying she was unhappy, not so much with her performance, but that we never talked about what she wanted to do with her money.

The second (same day) came when a good friend, with whom I had started my career, showed me some software he was using. I was fascinated, particularly because it put the client squarely in the center of the process.

Later that same day I received a phone call from Dave Loeper, an old friend and mentor from my Wheat First days and founder of a company I had invested in when he and I had left Wheat six years earlier. His company was known as Financeware. Dave, was calling regarding a deadline to get signatures from his angel investors.

Dave would spend the next hour and a half (time he really didn’t have) converting me from a performance manager to a wealth manager. He asked me a couple of questions that still resonate with me today. “Sam, what value do you bring to your clients?” My answer continued to belie acceptance of his assertions when I said, “I deliver portfolio returns to my clients that are superior to those they can get on their own or with indexes.” He then asked “can you guarantee that?” When I responded that obviously I could not, he asked one more time: “What value do you provide to your clients?”

In that moment it became clear that my clients deserved better than a performance-driven value proposition that is truly no more than a hope for success. I spent the next several months learning as much as I could about Financeware’s program known as Wealthcare. We converted our entire business model from a portfolio focus to a client focus. Conversations with clients became incredibly authentic. It is not an exaggeration to say that I learned more about my clients in the first hour of an initial Wealthcare plan meeting than I had learned in the 5, 10, or 15 years of managing their assets.

Validation that we had made the right choice came quickly. Client plans revealed significant opportunities that had been ignored by our portfolio/return-centric approach. We realized dramatic improvement in the goals our clients valued without sacrificing their current lifestyles. It became clear that the very methods I was using before to create opportunity for my clients was in fact creating uncertainty that hid or diminished them. For instance, in almost every case, we found that our clients were taking more risk than was required to meet or exceed their goals. As a result, our overall portfolio risk as a firm dropped substantially.


As you look at the graph above you can see there was a second drop of greater proportion in the S&P 500 index (in blue) and a much lower one in the NASDAQ (in red) in 2008 and 2009. Most of the nation’s banks and financial companies reside in the S&P 500. As they were hit the worst, the NASDAQ did comparatively better this time around.

So how did we do? We are focused on confidently meeting clients’ goals with sufficient wealth, not return, so graphics don’t tell the full story. Perhaps the greatest difference between 2000 and 2008 came in our telephone traffic. It pains me to think back to 2000 and the many panicked calls I fielded with little more than “stay the course, it will come back” for comfort.

In 2008/2009 our phones didn’t ring with the frenzied calls of 2000. Conversations were mostly prompted by us as we doubled and tripled our efforts to stay in touch through challenging times. When our clients asked how ‘we’ were doing, we offered them substantive information from their latest stress tests which showed they could be confident of meeting or exceeding their goals, despite market declines. It helped significantly that most had experienced significantly less volatility than the 37% declines of the S&P 500. In fact most (86%), required no changes to their plans as a result of the declines.

Today, with six years of Wealthcare experience for more than 75 families, I can happily say that our clients are empowered to live more abundant and purposeful lives as a result of our dramatic change in course. We and our clients no longer take life as it comes, we design lives with purpose.  

Friday, March 16, 2012

Confidence

What comes to mind when you hear the word confidence? You might think about the assurance of your own ability to accomplish a task or to succeed in some endeavor, great or small. You might also consider it as faith in somebody else; that they will do right or act in a trustworthy manner. Confidence in this light can also be associated with things that act in a predictable or reliable manner. It can mean a secret shared and it can describe the relationship of trust that exists to make sharing the secret possible.

One of the great fascinations during my thirty years plus in this industry has been observing how fragile and fleeting confidence can be in most every sense of the word - especially as it applies to self and to others. When things are going well and markets are rising, self-confidence reigns. Confidence in others, such as fund managers, is strong too, but it is quite fickle, landing on whomever produces the best results. And the faster markets rise, the shorter the duration that confidence remains in one place.

When the tide turns and markets begin falling, and doom and gloom replace the good news nearly overnight, self-confidence begins to fade for the stalwarts, and it evaporates like water on a hot skillet for the rest. They begin heading for the exits as fast as they can, with little regard for anything but getting into the relative safety of cash. This reaction is an understandable one. When there is nothing more than price to gauge confidence, its easy to understand how a sharp drop can elicit fear.

Others, instead of heading for the exits will choose to ‘hunker down’ and ride it out even though confidence in their managers is severely shaken, or even broken. Here is a fascinating phenomenon where people make a conscious decision to stick with managers in whom they have lost all confidence, yet still believe they are better off with them than leaving them. In other words, they have lost confidence in their own ability to choose better managers or more strangely, their need for continuity and consistency ironically supercedes their need for confidence.

There is another definition of confidence that we believe shines like a bright beacon for anyone struggling with uncertainty regarding his or her financial goals. It is that of statistical confidence. We use sophisticated probabilities analysis referred to by many as Monte Carlo analysis to provide confidence for our clients. But the process is complicated. You may not be completely clear on how it works and you might resaonably wonder if you can have confidence in the statistical results it produces.

Our process begins with a database of actual historical market returns (stock and Treasury) and  statistically possible returns. As Dave Loeper (designer of our system) points out, we are “able to measure not only the uncertainty of historical returns but also potential returns. This additional step [of including possible returns] helps us make sure we are not ignoring the chance that we have not yet seen the worst (or the best) of what the markets might produce.

So while we cannot predict the future of markets and how they will impact our client’s lives, we can measure the uncertainty of our client’s plan. The system does this by ‘living’ our client’s life plan (cash flow amounts and timing) virtually through all kinds of markets and it does it for 1,000 ‘lifetimes.’ The computer randomly draws market returns and calculates the impact that distinct return has on our client’s wealth relative to his cash flows, one year at a time for every year of his life and then it does it all over again 999 more times. The purpose is to gain an understanding of how confident we can be that our client will exceed his goals considering the uncertainty of market returns, including the very worst of them. With these numerous trials, our client ends up with many more outcomes than the one he was planning for; in other words, we've modeled the uncertainty of the future.

The figure below represents the potential outcomes for a couple living out a 32-year retirement on $65,000 annually (adj. for inflation without Social Security to keep it simple) using a $2 million portfolio (60% stocks, 40% US Treasuries, and cash). Each colored line represents a 10th percentile (there are 100 virtual lifetimes between each line). While the chances for any one of the outcomes to occur are equal, notice how wide the range of potential outcomes is on the right-hand side of the graph. The analysis suggests our couple could end their lives $3.1 million in debt or they could just as likely die with $12.1 million in wealth; and there are 998 additional possibilities in between.

(C) Wealthcare Capital Management, Inc.                                            

So how do we gain any confidence from all these lines and uncertainty? The graph clearly demonstrates how vulnerable to uncertainty one is if historical market returns are his only guide to financial confidence; he can only react to what has happened. We take a proactive approach. With this tool, we can measure the uncertainty our clients will experience as they demand from the markets the wealth required to accomplish or exceed their goals.

Notice that most of the lines end above zero. In fact, 830 of them representing virtual lives lived experienced market returns sufficient to meet or exceed our couple’s needs for $65,000 annual spending, adjusted for inflation. Remember, we used a $2 million portfolio (60%/40%) that would be drawn down to zero. Based on the analysis then, our couple can be 83% confident of meeting or exceeding their goals.

But confidence is fleeting, you might say. What happens in the real world when a 2008 comes crashing in and the S&P drops 38%? Let’s say our couple began a relationship with us December 31, 2007. During 2008 our Balanced model (60%/40%) lost 19.7% so our couple’s portfolio would be down to $1,541,000 after taking their $65,000 withdrawal for income. Certainly, that drop might rattle anyone who has nothing more than CNBC or the hollow promise that 'it will come back in time' on which to base his confidence.

During our hypothetical December client meeting, we informed our clients that there was a 17.3% chance of their portfolio becomming under-funded in its first year due to market volatility. In wealth terms that translated to $1,436,072. As their portfolio stood at $1,541,000, the couple's confidence remained above our comfort threshold of 75% so no portfolio or spending changes were required.

(C) Wealthcare Capital Management, Inc.

The plan report that we presented our clients would have included a lifetime snapshot of where their investment portfolio needed to be in today’s dollars for each of their remaining years in order to provide sufficient confidence of meeting or exceeding their income goals.

A picture of confidence is worth a thousand virtual lives !


(C) Wealthcare Capital Management, Inc.

Look again at the table entitled "Chance of Falling Outside the Comfort Zone." It indicates that just in the first year, there is a 41.6% chance our couple will be outside what we consider an acceptable range of confidence. Because of this broad range of potential outcomes in a relatively short period of time we continually stress test our clients' plans against new information to indentify opportunities or risks when their plans become over- or under-funded, respectively. Without a tool like this, determining life-plan confidence is nothing more than guesswork and guesswork is not effective life planning.

Have a nice weekend.

Friday, March 9, 2012

Boomers Take Note

The week’s economic numbers continued their trend toward improvement with manufacturing store sales, consumer confidence, and jobs growth all moving ahead. Even Greece looks to end the week on a strong note as arm-twisting forced enough bondholders to swallow losses of more than 100 billion euros ($132 billion) and allow the beleaguered country to move forward with its next phase of debt re-structuring.

Jobs growth continued at a reasonably healthy pace in February, according to the government. The gain of 227,000 jobs followed gains of 284,000 in January and 223,000 in December. Jobs were produced primarily in the services industries of the private sector. By industry, job gains were strongest in professional and business services, health care and social assistance, and leisure and hospitality, according to Econoday. Average hourly earnings rose a modest 0.1% in February, following a 0.1% gain the month before. The average workweek for all workers in February was unchanged at 34.5 hours. According to the household survey, the unemployment rate remained steady at 8.3% as the pool of available workers rose as fast as new jobs were created.

Consumer confidence is on the rise as more Americans said the economy was improving, according to the Bloomberg Consumer Comfort Index. The index rose to a minus 36.7 in the period ended March 4th, the highest since April 2008 and up from minus 38.8 in the prior period. The gauge on the state of the economy reached a one-year high while the buying-climate measure climbed to a level last exceeded in December 2009. Joe Brusuelas, a senior economist at Bloomberg said consumers are much more comfortable about their own personal financial situations, which is largely negating the recent rise in gasoline prices.” But he also noted index remains at the low end of its historical range.

Consumers took their improved moods shopping last week according to Goldman Sachs and Redbook. Goldman’s weekly same-store sales index rose 1.3% in the week ended March 3rd, while Redbook’s index saw a 3.0% rise of year-on-year same store sales ended March 2nd. This rate compared to a 3.4% gain the prior week. Redbook sees stronger sales ahead for the month ahead.

The ISM reported that its non-manufacturing index rose 0.5% to 57.3. Econoday says the composite may understate underlying strength in the bulk of the nation's economy where order levels are building with new orders up nearly two points to a very strong 61.2 vs. January's already very strong 59.4. The index is comprised of agriculture, mining, construction, transportation, communications, wholesale trade and retail trade companies.

The manufacturing sector cooled modestly as factory orders fell back 1.0% following very strong gains in the prior months of 1.4% and of 2.2%. Weakness was centered in durable goods orders which fell 3.7%. Orders for non-durable goods, which always reflect price swings in commodities especially oil, rose 1.3%.

Boomers Take Note
An article this week caught my attention as an example of how terrible financial advice can be taken as sound by it's association with the presenter; in this case the Wall Street Journal. The article was titled Testing the 4%-a-Year Retirement Rule and features Bill Bengen, a financial planner in Southern California who developed the 4% rule.

The following description of his rule is excerpted from the article: “In a study published in 1994, he said that if retirees withdrew 4% of their nest egg in the first year, and then increased the dollar amount by the inflation rate every year, their savings would easily last 30 years. He assumed that the portfolio was held in a tax-deferred account and was evenly split between large-company stocks and U.S. Treasury bonds. In a subsequent study, Mr. Bengen added U.S. small-company stocks to the mix, which increased the portfolio's volatility and potential return. To adjust for this, he revised the withdrawal rule to 4.5%.”

The first problem is with the article itself. There was no testing to be found. The author merely points out that as stocks have become more volatile, many wonder whether Mr. Bengen's rule still holds. The answer?: Well, Mr. Bengen says he thinks it does. However, he says the next five years could be crucial, particularly for individuals who retired in 2000 and have experienced two major stock-market downturns since then. He expects stock returns to be low for a while; if that is coupled with high inflation rates, "then retirees have a big problem," he says.

In my view Mr. Bengen’s ‘rule’ has several problems. While it seemingly addresses inflation, it ignores capital market uncertainty. Uncertain returns (portfolio values) mean that spendable income (4.5% of portfolio plus inflation) will swing wildly from one year to the next. My experience is that people really don’t like their income to swing.

Take for example a couple with a million dollars to spend over their remaining 30-year retirement. Mr. Bergen’s examples use a deferred account invested in a balanced portfolio (60% equities and 40% fixed) so we will too. Using our Monte Carlo system to live our couple’s lives virtually 1,000 times through randomly generated capital market returns (against an allocation of 60% equities and 40% fixed) we find that their income would range significantly depending upon the kinds of market returns they would experience.

Lowest
Highest
Income
Income
25th Percentile - Good Markets
$34,376
$65,038
50th Percentile - Average
$36,335
$66,382
75th Percentile - Poor Markets
$30,396
$49,012
In today's dollars

Here’s how the cash flows look under these three lifetime scenarios.


The picture above illustrates why so many throw their hands up and buy annuities, which are basically contracts which pay the insurance company to give them back their own money.

There’s another huge problem with Mr. Bengen’s rule of 4.5%. Look below at all the money our couple would have left over at their deaths; money that they may have wanted to use during their lives. Even at the 75th percentile, the most pessimistic of our examples above, the couple left $783,832 in the bank, unspent. OK, they may have heirs to whom the money might have gone. But shouldn’t the donors get the chance say how much?


Here’s a better way.

Take our same couple, assuming the same portfolio and risk allocation of 60% stocks and 40% bonds. But this time, let’s suggest that instead of accepting a lifestyle dictated by their returns let’s give them the opportunity to do some dictating themselves. We would ask them what level of spending might be ideal as well as what would minimally suffice if other more important goals required it. In this case our only other goal is to leave something for the kids.

Our couple tells usthat it would be ideal for them to spend $45,000 (after-tax) annually (adj. for inflation) for the rest of their retired lives. If necessary their spending could be reduced to $40,000. They would ideally like to leave their children $100,000, but not less than $50,000.

We inform our couple that they could accomplish both goals at their ideals and have an 81% confidence of exceeding both goals. Our objective is to maintain, to the extent possible, our clients’ income and estate goals through actual market turbulence and the uncertainty of future markets. By continually measuring uncertainty in our clients’ plan we can make adjustments to their spending, estate, and portfolio risk (allocation) according to their priorities to maintain a comfortable level of confidence.


The table above illustrates the broad range of potential outcomes for a $1 million portfolio delivering an annual after-tax income level of $45,000 (adj for inflation) and ending with $100,000. There is a 75% chance the portfolio will be worth more than $300,000 at death and a 25% chance that it will exceed $2.1 million. It is a picture of why our couple needs professional assistance in managing the uncertainty ahead of them and why a simple 4.5% rule of thumb simply won’t do.

Have a nice weekend.